
If you've been thinking about buying a home but have put the brakes on due to current interest rates, you're not alone. Many buyers are sitting on the sidelines, hoping interest rates will come down before making a move. And when that happens, we’re going to see a huge influx of buyers in the market. Housing prices will go up. Competition will go up.
So here's something worth knowing: There may be ways to make your initial mortgage payments more manageable without waiting for rates to drop. And the good news is that because there are currently fewer buyers, sellers are frequently more open to negotiation – and you won’t necessarily be competing with other offers. In fact, I’ve currently seen several homes priced below assessment!
So what does ‘get creative’ mean? There are a lot of loan options out there that can ease you into home ownership at a potentially lower rate. Here are a couple of examples (and a lender can help you explore ALL of your options)
2-1 mortgage buydown
One option that's getting attention is called a temporary mortgage rate buydown. Some lenders offer programs that reduce a buyer's interest rate for the first couple of years of their mortgage, giving them a little breathing room while they settle into homeownership.
Here's how it works:
Year One: Your interest rate is reduced by 2 percentage points below your contracted mortgage rate.
Year Two: Your interest rate is reduced by 1 percentage point.
Year Three and Beyond: Your regular, contracted interest rate takes effect.
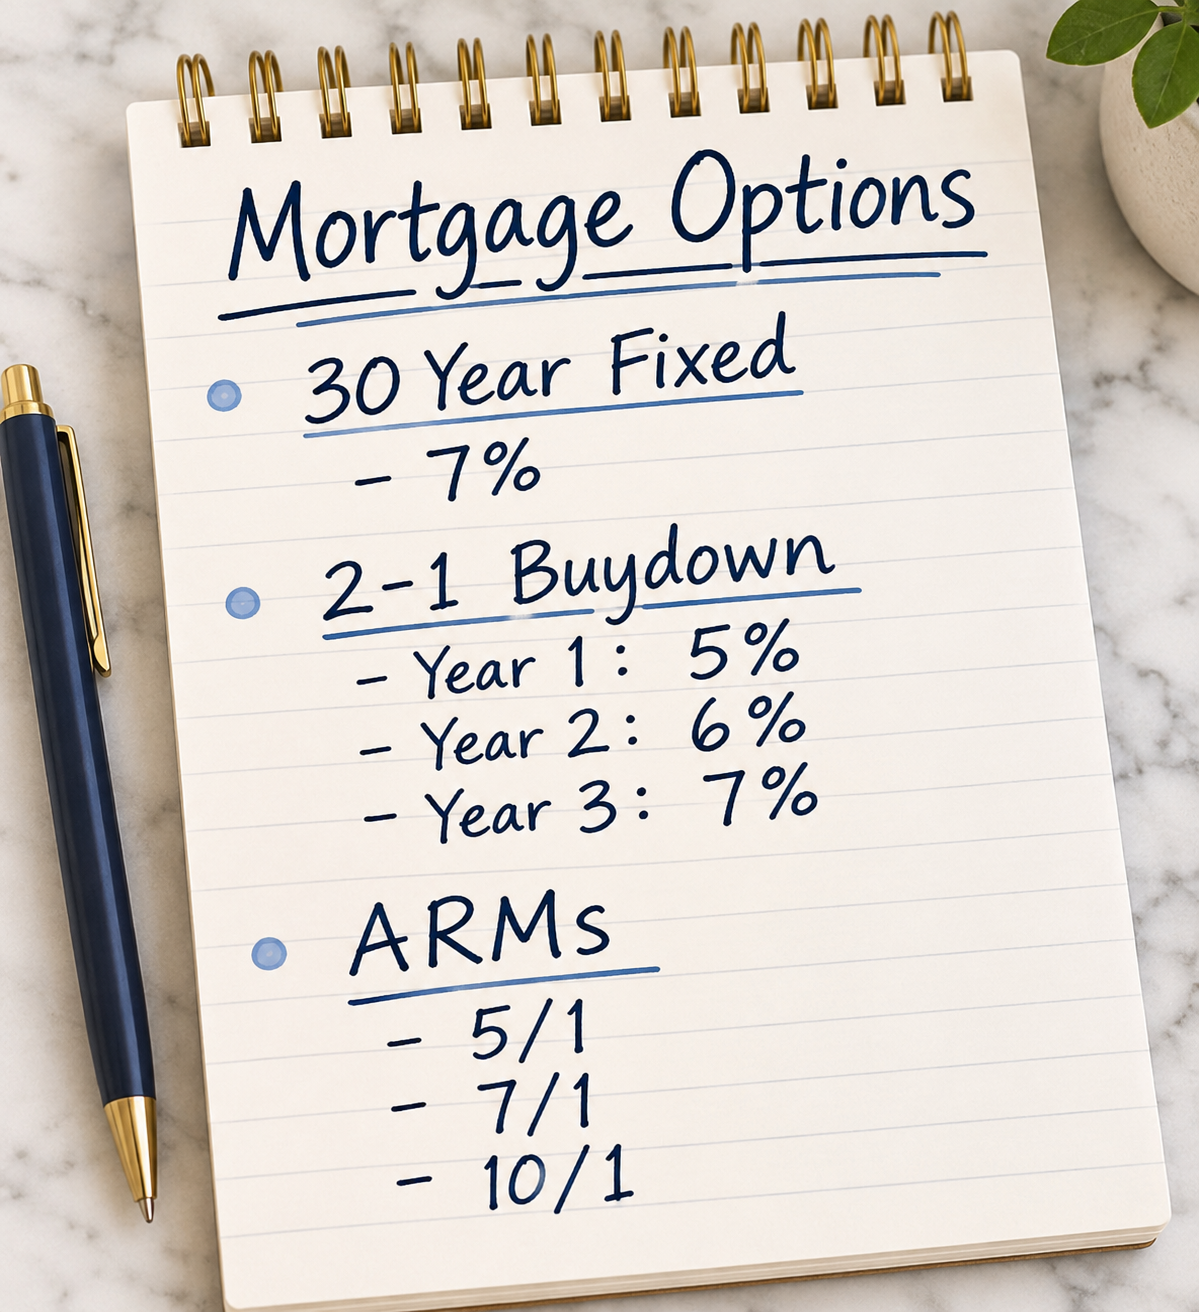
For example, if your permanent mortgage rate is 7.0%, your rate would be 5.0% in the first year, 6.0% in the second year, and 7.0% in year three. That can translate into meaningful monthly savings during those first two years when you're also dealing with moving expenses, furnishing a new home, and all the little costs that come with homeownership. And while it’s no guarantee, you do have two years in which rates just might drop. And when/if that happens, you can always refinance at the lower rate.
Who pays for the lower rate?
A temporary buydown isn't free money. The cost is essentially the difference between the payments at the reduced rate and the payments at the full mortgage rate.
Depending on the program, the cost may be covered by the seller, a builder, or the lender as part of a promotion. In some transactions, buyers can also negotiate a seller contribution toward the buydown. I’ve seen quite a few sellers offering this as an incentive.
This is where having a good real estate agent can make a difference. In certain situations, negotiating a seller credit toward a mortgage buydown may be more valuable to a buyer than negotiating a small reduction in the purchase price.
Is it right for everyone?
Not necessarily. There are a few important things to understand:
Buyers generally must qualify for the mortgage using the full, permanent interest rate.
The payment increases in year two and again in year three, so you need to be comfortable with the eventual payment.
Not every loan program or buyer qualifies for every promotion.
It's important to compare the total cost of the loan, including closing costs and the permanent interest rate, with other available financing options.
A temporary buydown can be particularly attractive to buyers who expect their income to increase, anticipate other expenses to decrease, or simply want a little financial flexibility during their first couple of years in a new home.
Don't overlook the negotiating opportunities
Another reason I encourage buyers to explore creative financing is that today's market can offer opportunities that weren't as common when homes were selling almost as soon as they hit the market.
Depending on the property and the seller's circumstances, there may be room to negotiate closing-cost assistance, a rate buydown, repairs, or other concessions.
And sellers shouldn't overlook these strategies either. Offering a financing incentive may help make a property more attractive to buyers without necessarily reducing the asking price.
ARMs (Adjustable Rate Mortgages)
You may have heard of a 5/1 or a 7/1 ARM. An adjustable rate mortgage is a loan where the interest rate stays the same for an initial period of time (and is generally .5 to 1% less than current rates) and then periodically adjusts after the initial period. The first number represents the number of years the rate is fixed. The second number represents the frequency that the rate will adjust, according to market conditions, following the fixed period. So in the case of a 5/1 arm, the rate will adjust annually beginning the sixth year along with current market conditions.
A lot of people don’t trust ARMs. They view it as too risky. What if rates spike after your fixed period? But you need to think of this as a tool and a stepping stone. If today’s rates are the only thing holding you back, it’s worth considering. Depending on which program you choose, your rate will stay fixed for five, seven or even ten years. And you can refinance at any point, and can always go with a 30 year fixed at a better rate than what’s being offered today.
This can be a great option for homebuyers who know this is not their forever home. If your plan is to build some equity and sell within 5 or 7 years, it’s a definite win. It can also be a smart choice for those who want to buy before the market goes into high gear, with the idea that they will refinance when the rates drop.
The bottom line
You don't necessarily have to wait for mortgage rates to fall before exploring homeownership. There are financing options, lender incentives, and negotiating strategies that may make buying a home more affordable right now.
My advice? Don't assume you can't afford to buy until you've explored the possibilities. Talk with a knowledgeable lender, compare your options, and look at the entire financial picture. It’s free with no obligation, and all it takes is a SOFT credit pull.
And if you're considering buying or selling in Charlottesville or the surrounding counties, I'm always happy to help you explore the possibilities. Sometimes a little creativity and the right strategy can make all the difference.